Market Commentary
Read the Fall 2026 WAA for our Q3 | 2026 QuickTakes, The Outlook, and Much More
November 2026
Market Leadership Shifted in October,
as Technology Retreats and Bonds Rally
October brought a sharp reversal in market leadership, reinforcing the importance of diversification across investment styles, company sizes, and asset classes. Technology shares retreated as investors questioned the long-term payoff from substantial artificial intelligence spending, while value stocks, smaller companies, and bonds offered brighter spots. And all in advance of midterm elections.
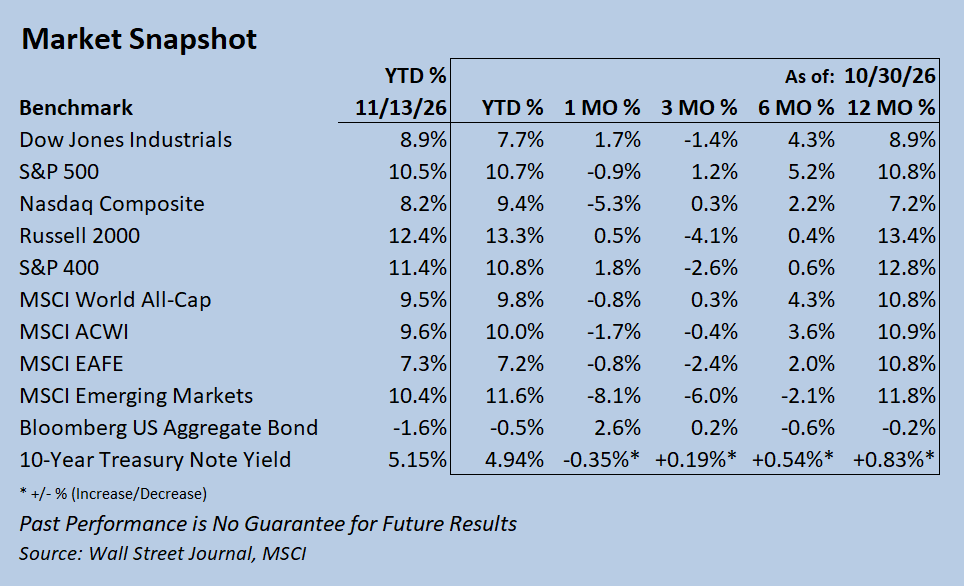
After reaching record highs in September, the technology-heavy Nasdaq declined 5.3% in October. The broader S&P 500 slipped 0.9%, while the Dow Jones Industrial Average gained 1.7%. Large-cap value stocks outperformed large-cap growth by more than 10 percentage points, according to Nasdaq, highlighting the month’s pronounced shift in investor preferences.
Performance also improved beyond the largest U.S. companies. The S&P MidCap 400 led the major domestic indexes with a 1.8% gain, while the small-cap Russell 2000 edged up 0.5%.
International markets experienced uneven declines. The developed-market MSCI EAFE Index slipped 0.8% as the European Central Bank maintained policy rates. The MSCI Emerging Markets Index fell 8.1%, with losses concentrated in Korea, Taiwan, and Brazil, alongside changes in the index’s composition.
Economic Resilience Meets Persistent Inflation
The U.S. economy remained generally resilient, with third-quarter GDP expanding at a robust 3.4% pace and corporate earnings remaining strong. Softer-than-expected labor data, however, added a note of caution amid persistent inflation, elevated energy costs, and geopolitical uncertainty.
September’s Consumer Price Index showed inflation running at 3.7% over the preceding 12 months, while wholesale prices rose 6.3%. Renewed tensions surrounding the Iran war added pressure, sending oil prices approximately 15% higher in October to $104 per barrel.
The Federal Reserve held policy interest rates steady at its October 27–28 meeting, as widely expected. Nevertheless, market expectations for a quarter-point increase at the December meeting remained elevated.
Bonds Rebound as Treasury Yields Decline
Despite ongoing inflation concerns, Treasury yields reversed lower after reaching year-to-date highs early in October. The benchmark 10-year Treasury yield ended the month at 4.94%, down 35 basis points, or 0.35 percentage point. Shorter-term yields edged modestly lower.
Falling yields supported a strong bond-market recovery. The Bloomberg U.S. Aggregate Bond Index gained 2.6% in October, narrowing its year-to-date decline to 0.5%.
November Update:
Post-Election Swings, Nvidia Uncertainty, and Rising Rates
November began with heightened volatility as investors weighed the midterm election results and their implications for economic policy and technology investment. Democrats’ gains, securing control of both chambers of Congress, initially sparked a relief rally. That optimism quickly gave way to concerns that greater scrutiny of artificial intelligence infrastructure could slow data-center development. A sharp technology-led selloff followed, with the Nasdaq-100 falling approximately 6% on November 5, while the S&P 500 fell 4.4%.
Stocks subsequently recovered some ground, although trading remained unsettled. The S&P 500 gained 2.5% during the week ending November 13, despite declining 0.4% on Friday. The Nasdaq Composite also posted a weekly advance, breaking a four-week losing streak. Despite recent volatility, major U.S. stock indexes maintained solid year-to-date gains through November 13, led by double-digit advances in the S&P 500, Russell 2000, and S&P MidCap 400.
Nvidia added another source of uncertainty after Jensen Huang resigned as chief executive on November 12, with Chief Financial Officer Colette Kress assuming the interim CEO role. The unexpected transition raised questions about leadership continuity and execution at a company central to the AI investment cycle. Nvidia’s extensive industry relationships and substantial index weighting amplified the market’s sensitivity to the news, adding to existing concerns about whether AI profits will justify substantial spending and elevated valuations. Nvidia is the world’s second-largest company by market capitalization and a major holding in many large-cap stock indexes and investment funds.
Inflation Reports Push Interest Rates Higher
Fresh inflation reports challenged hopes for a sustained easing in price pressures. October’s Consumer Price Index, released November 10, rose 0.4% for the month, while core prices excluding food and energy increased 0.3%. Both exceeded expectations, reinforcing concerns that inflation was extending beyond energy. An official headline year-over-year CPI rate was unavailable because the 2025 government shutdown interrupted collection of the October comparison data.
The November 13 released Producer Price Index report offered only partial reassurance. Wholesale prices increased 0.3% in October, a smaller monthly gain than September’s surge, but the annual increase accelerated to 6.5%—the strongest since November 2022.
Treasury yields moved sharply higher as investors reassessed the Fed’s policy path. The benchmark 10-year yield finished November 13 near 5.15%, reversing October’s decline and rising approximately 30 basis points during the week. Markets increasingly anticipated a quarter-point December rate hike, with a larger half-point increase also under discussion. Expectations for additional tightening extended into 2027.
Investor Perspective
October and early November underscored how quickly market leadership and interest-rate expectations can reverse. October’s bond rally gave way to renewed pressure from rising yields, while technology stocks faced questions about AI spending, potential policy changes, and leadership at a major industry participant.
For investors, these developments reinforce the value of diversification across investment styles, company sizes, geographic markets, and bond maturities. Diversification cannot eliminate losses, but it can help reduce dependence on a handful of companies or a single economic outcome. Within fixed income, balancing income opportunities with sensitivity to rising rates remains particularly important.
Our focus remains on maintaining disciplined allocations aligned with clients’ objectives, liquidity needs, and tolerance for risk. We remain cautiously optimistic, as markets evaluate incoming inflation data, corporate results, and the Fed’s next steps. Selective rebalancing and a long-term perspective remain valuable tools for navigating near-term uncertainty.
As we look toward year-end, several key issues will remain on investors' watchlists:
• It's RMD Season and time to begin year-end planning
• Remain well-diversified
• Maintain discipline and patience
• Keep your focus on the long term
• Review your risk tolerance
Call your Nelson Advisor today at 800-345-7593 to discuss your portfolio, your financial goals, or any concerns you may have about current market conditions.
~ Your Nelson Securities Team
Past Performance is No Guarantee for Future Results
This article is for informational purposes only and does not constitute investment advice.